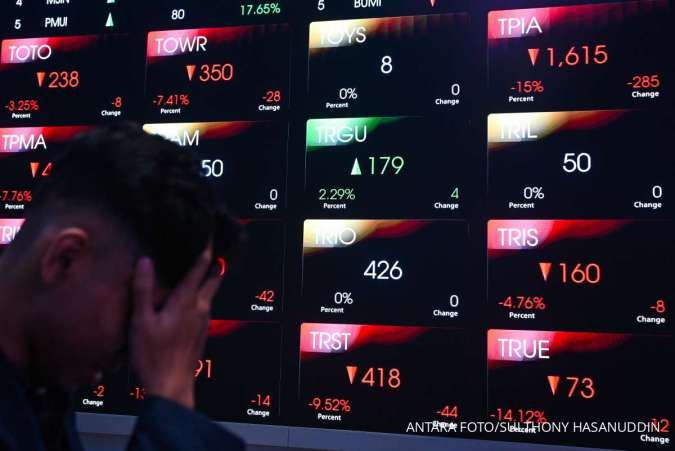
KONTAN.CO.ID - Foreign institutional investors are adopting a cautious, highly gradual accumulation strategy toward Indonesian equities as a sharp structural contraction in the nation's global index weighting limits massive cross-border capital inflows. According to an institutional research report published by
CGS International Sekuritas on September 15, 2026, foreign portfolio managers logged a neat net inflow of US$155 million during the first week of September. While the capital reversal signals expanding trust in the central government’s market-friendly policy baseline, underlying cross-border momentum is heavily capped by index allocation dynamics.
Baca Juga: UBS Sells 1.19 Million CPIN Shares in Jakarta for Derivative Hedge The 0.5% MSCI Weighting Friction and Regional Comparisons
Hadi Soegiarto, equity analyst at CGS International Sekuritas, revealed that international attention toward Jakarta assets has thin coverage compared to historical benchmarks. "Indonesia’s weighting within the MSCI APAC ex-Japan Index has collapsed to just 0.5%, eroding foreign fund visibility compared to the 1.2% weighting held in December 2025," Soegiarto clarified. This tracking reduction places Indonesia’s market exposure at a deep structural disadvantage against regional peers as of August 2026:
- Thailand: Commands nearly double (200%) of Indonesia's index weight.
- Malaysia: Holding 200% of Indonesia's allocation footprint.
- Singapore: Dominating with a weight over 7 times larger (714%) than the Indonesian asset pool.
Because of this low institutional weight, macro perambulations and positive domestic regulatory fixes require extended time horizons to effectively translate into broad-based foreign inflows. Global managers are choosing to execute longer observation cycles to ensure structural policy continuity before locking in multi-year capital allocations.
Baca Juga: Indonesia to Receive Assistance From Malaysia to Contain Wildfires Fiscal Deficits and the Looming November MSCI Review
The baseline thesis for an eventual equity index recovery to historical 2025 levels remains heavily dependent on the upcoming MSCI index review in November 2026. CGS International's base case maps out a continuation of the current "freeze" status without an outright asset downgrade. While any extension of the freeze framework limits high-frequency quantitative buying, global desks emphasize that concrete domestic fiscal and monetary execution takes precedence over rigid index rules. On the fiscal front, foreign funds are tracking the new Finance Minister's capacity to aggressively rein in national fiscal deficits amid elevated global crude oil inputs and expanding domestic subsidy burdens. Monerarily, the focus remains on Bank Indonesia’s (BI) defense layout to shield the Rupiah from an increasingly hawkish US Federal Reserve.
Baca Juga: Indonesia’s ULTJ Plots Rp16.9 Trillion Rights Issue for FFI Acquisition Despite these macro hurdles,
CGS International maintained a constructive outlook under the operational theme "Half the weight, double the effort." To outrun index friction, international asset desks are concentrating capital heavily into defensive top-tier large caps, officially listing BBCA, BBNI, ASII, and adding BBRI into its premier focus portfolio on expectations of swift near-term operational metric improvements and premium asset quality recoveries.