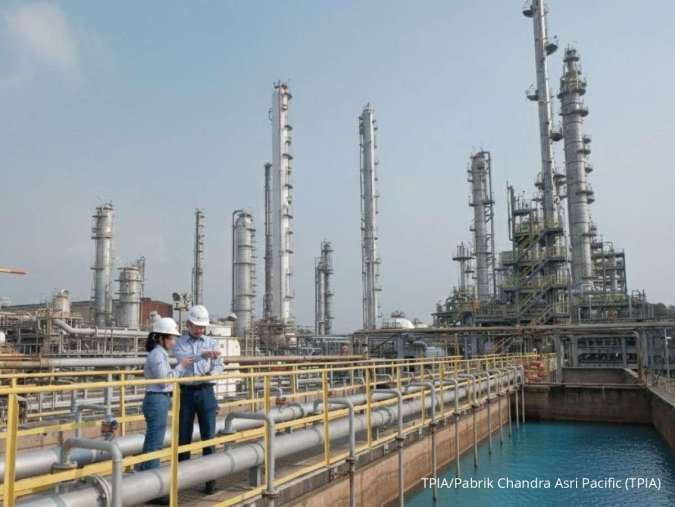
KONTAN.CO.ID - Global chemical supply chains are facing severe structural bottlenecks, pushing methanol benchmarks up by a massive 60.44% over the past month according to Trading Economics data up to September 11, 2026. While the sudden price spike has injected positive sentiment into Indonesia’s premier chemical conglomerate, PT Chandra Asri Pacific Tbk (TPIA), market analysts warn that the rally does not act as a direct proxy for immediate earnings acceleration. Senior Market Analyst Nafan Aji Gusta from Mirae Asset Sekuritas noted that because methanol is not TPIA's primary revenue anchor, the absolute price movement offers limited direct bottom-line impact. Instead, the focus must remain squarely on wider petrochemical spreads—the margin between downstream product prices (olefins and polyolefins) and raw naphtha feedstock costs.
Geopolitical Friction and the Straits of Hormuz Factor
The underlying catalyst behind the 60% methanol surge reflects tight chemical supply networks across Asia rather than booming demand. The commodity found intense pricing support following low utilization rates among Iranian chemical processors and escalating maritime trade disruptions running through the Straits of Hormuz. "The rally represents a geopolitical risk premium rather than a structural upcycle," stated Investing Journey ID founder Briant Stevanus. For TPIA, the corporate risk structure is dual-faceted:- Legacy Cilegon Petrochemical Assets: Surging crude and naphtha prices (up 25% in some tranches) risk squeezing chemical processing margins if feedstock costs outrun final product selling rates.
- Integrated Assets via Aster Singapore: TPIA’s recent acquisition of integrated refinery and cracker infrastructure acts as a strategic hedge, allowing the firm to capture enhanced Gross Refining Margins (GRM) to offset raw material cost pressures.